There has been considerable discussion about the entry into force of the Law on Mandatory Health Care Insurance, but let us translate the provisions into concrete figures.
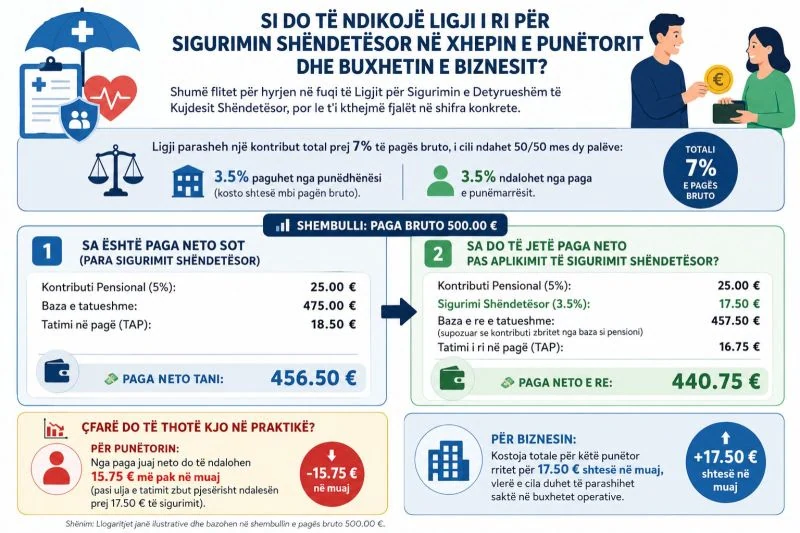
The law provides for a total contribution of 7% of gross salary, divided equally between the two parties:
- 3.5% is paid by the employer as an additional cost above gross salary.
- 3.5% is withheld from the employee’s salary.
Example: Gross salary of €500.00
1. What is the net salary today, before health insurance?
- Pension contribution (5%): €25.00
- Taxable base: €475.00
- Payroll tax: €18.50
- Current net salary: €456.50
2. What would the net salary be after health insurance is applied?
- Pension contribution (5%): €25.00
- Health insurance (3.5%): €17.50
- New taxable base: €457.50, assuming the contribution is deducted from the tax base in the same way as the pension contribution.
- New payroll tax: €16.75
- New net salary: €440.75
What does this mean in practice?
- For the employee: monthly net salary decreases by €15.75, as the lower tax partially offsets the €17.50 insurance deduction.
- For the business: the total cost of this employee increases by an additional €17.50 per month, an amount that should be accurately reflected in operating budgets.
#Accounting · #Kosovo · #Finance · #Payroll · #HealthInsurance · #ACCA · #BusinessStrategy · #Taxation